Not because they’re lazy or careless—but because these habits quietly block progress over time
Talking about “money habits that keep people poor” can feel uncomfortable. Too often, this topic is used to shame people who are already struggling, as if financial difficulty is simply a matter of bad choices or weak discipline.
That narrative is incomplete—and harmful.
The truth is more nuanced. Many people remain financially stuck not because they don’t work hard, but because certain habits—often learned out of necessity or stress—slowly drain stability and momentum. These habits are common, understandable, and often invisible to the people practicing them.
This article explores those habits honestly, without judgment. The goal isn’t to assign blame—it’s to bring awareness. Because once you understand what’s holding you back, you can start changing direction in ways that actually work.

First, an Important Reality Check
Before diving in, this needs to be said clearly:
Poverty is not a character flaw.
Structural issues—wages, housing costs, healthcare, education, geography—play a massive role in financial outcomes.
However, within those constraints, habits still matter. Not because they magically fix everything, but because they can either:
-
Protect what little stability exists, or
-
Quietly erode it over time
This article focuses on the second category.
Habit #1: Living in Constant Financial Reaction Mode
One of the most damaging habits is living in reaction mode instead of planning mode.
This looks like:
-
Paying bills only when they’re due (or overdue)
-
Using credit cards for surprises
-
Making financial decisions under pressure
-
Constantly putting out fires instead of preventing them
When money is tight, reaction mode feels unavoidable. But over time, it becomes a pattern that keeps people stuck.
Why this keeps people poor
Reaction mode leads to:
-
Late fees
-
High-interest debt
-
Stress-based decisions
-
No room for strategy
Money ends up controlling you instead of the other way around.
What helps instead
You don’t need a perfect plan—just one step ahead:
-
One-week or one-month planning
-
A small buffer (even $100 changes behavior)
-
Automating what you can
Moving from reaction to anticipation is a major shift.
Habit #2: Treating Savings as Optional
Many people save only “if there’s money left.”
Most months, there isn’t.
When saving is optional, it’s always the first thing to go—especially during stressful periods.
Why this keeps people poor
Without savings:
-
Emergencies turn into debt
-
Small setbacks wipe out progress
-
Stress increases, leading to worse decisions
-
Every problem feels urgent and expensive
Lack of savings doesn’t just affect money—it affects mental bandwidth.
What helps instead
Saving must become automatic and boring, not aspirational.
This means:
-
Saving first, not last
-
Starting small (very small counts)
-
Treating savings like a bill
Consistency matters more than amount.
Habit #3: Relying on Credit to Maintain a Lifestyle
Credit cards and buy-now-pay-later options often fill the gap between income and lifestyle.
People use them to:
-
Smooth income gaps
-
Handle emergencies
-
Keep up with expectations
-
Avoid uncomfortable trade-offs
While credit can be useful, relying on it to maintain normalcy is dangerous.
Why this keeps people poor
Credit:
-
Masks income shortfalls
-
Adds interest to basic living costs
-
Delays necessary changes
-
Turns small problems into long-term ones
Debt reduces future flexibility—and flexibility is crucial for progress.
What helps instead
Credit should be strategic, not emotional.
That means:
-
Using it intentionally, not automatically
-
Avoiding lifestyle maintenance on credit
-
Prioritizing cash flow stability over appearances
Habit #4: Ignoring Small, Repeating Expenses
Many people focus on big bills and completely overlook small, recurring expenses.
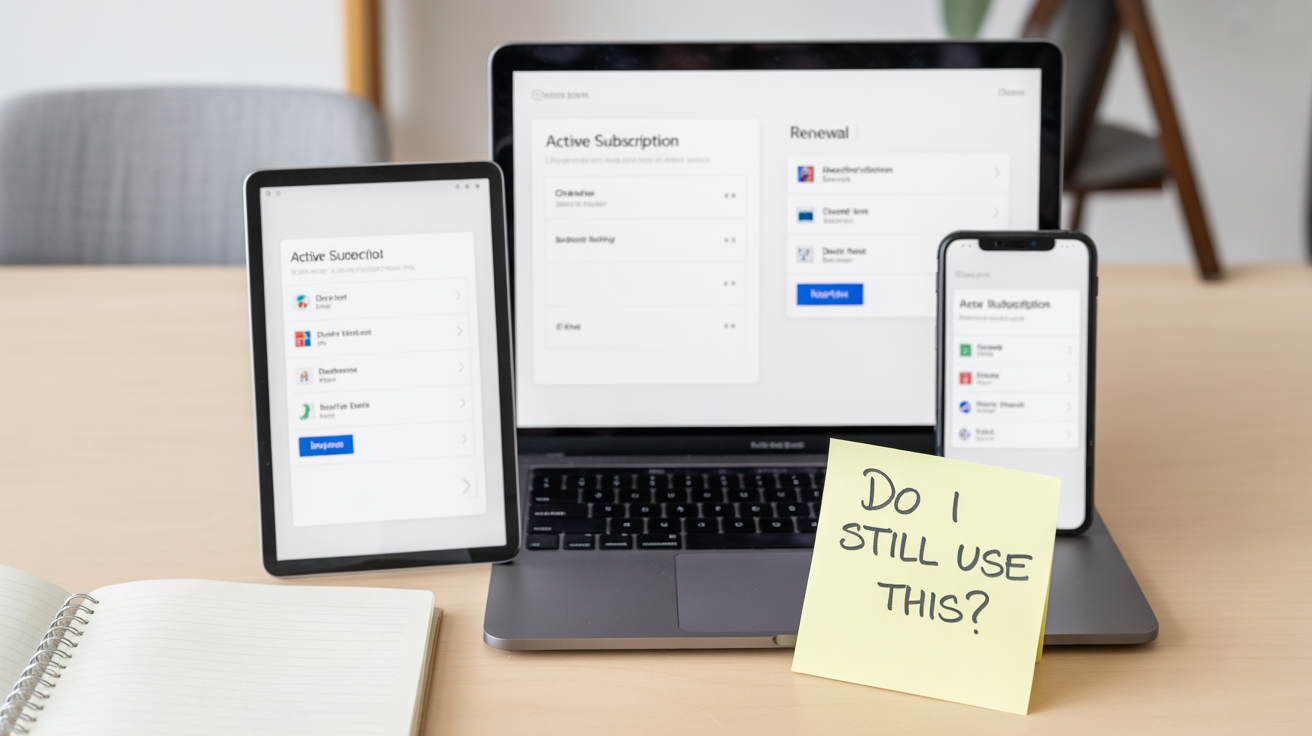
Subscriptions, app fees, convenience purchases, service charges—these don’t feel significant individually, but together they drain cash quietly.
Why this keeps people poor
Small leaks:
-
Reduce available cash
-
Make budgets feel “tight” without explanation
-
Prevent savings from sticking
-
Create reliance on credit
The problem isn’t occasional treats—it’s untracked accumulation.
What helps instead
Periodic awareness—not constant restriction.
A simple fix:
-
Review spending every 30–60 days
-
Identify recurring charges
-
Decide intentionally which ones stay
Control comes from awareness, not deprivation.
Habit #5: Not Planning for Irregular Expenses
Car repairs. Medical costs. Annual subscriptions. Gifts. School expenses.
These aren’t emergencies—they’re predictable irregular expenses. Yet many budgets ignore them.
Why this keeps people poor
When irregular expenses aren’t planned for:
-
Credit cards become the default
-
Budgets feel like they “never work”
-
Progress gets erased repeatedly
-
Financial confidence erodes
What helps instead
Use sinking funds:
-
List predictable non-monthly expenses
-
Divide by 12
-
Save small amounts monthly
This simple habit reduces chaos dramatically.
Habit #6: Comparison-Based Spending
Social pressure is one of the most powerful—and invisible—drivers of poor financial decisions.
People overspend to:
-
Keep up with peers
-
Avoid feeling left behind
-
Match perceived “normal” lifestyles
-
Protect their self-image
Social media amplifies this effect by showing curated lives without context.
Why this keeps people poor
Comparison-based spending:
-
Disconnects spending from values
-
Encourages upgrades before readiness
-
Turns progress into pressure
-
Makes “enough” feel unreachable
What helps instead
Shift the reference point:
-
Compare yourself only to your past self
-
Define success on your own terms
-
Reduce exposure to triggering content
Quiet progress is still progress.
Habit #7: Extreme Frugality Followed by Burnout
Many people swing between two extremes:
-
Very strict budgeting
-
Complete abandonment after burnout
This cycle is exhausting—and expensive.
Why this keeps people poor
Over-restriction leads to:
-
Rebound spending
-
Guilt
-
Giving up entirely
-
Repeating the cycle
Discipline without sustainability doesn’t last.
What helps instead
Balanced budgeting:
-
Include room for small joys
-
Plan flexibility
-
Focus on consistency, not perfection
A budget should support your life—not punish it.
Habit #8: Avoiding Money Conversations and Numbers
Avoidance is a coping mechanism.
Many people avoid:
-
Checking balances
-
Opening bills
-
Reviewing debt
-
Talking about money
Not because they don’t care—but because money is emotionally loaded.
Why this keeps people poor
Avoidance:
-
Allows problems to grow
-
Leads to fees and penalties
-
Increases anxiety
-
Removes control
Ignoring money doesn’t make it disappear—it makes it louder.
What helps instead
Gentle, regular check-ins:
-
Weekly or biweekly reviews
-
Short, non-emotional sessions
-
Focus on patterns, not mistakes
Clarity reduces fear.
Habit #9: Believing Income Is the Only Thing That Matters
Income matters—but habits determine how income behaves.
Some people earn more but stay broke. Others earn less and build stability.
Why this keeps people poor
If income increases without habit changes:
-
Spending rises just as fast
-
Debt persists
-
Progress stalls
Money habits shape outcomes.
What helps instead
Treat income increases as opportunities to:
-
Increase savings first
-
Reduce debt
-
Build buffers
-
Improve stability—not just lifestyle
Habit #10: Internalizing Financial Struggle as Personal Failure
This may be the most damaging habit of all.
When people believe they are “bad with money,” they:
-
Stop trying
-
Avoid learning
-
Feel shame instead of curiosity
-
Make worse decisions under stress
Why this keeps people poor
Shame paralyzes growth.
What helps instead
Reframe money as a skill, not a moral trait.
Skills can be learned. Systems can be built. Habits can change.
What Actually Breaks the Cycle
People don’t escape financial struggle through extreme discipline or perfect plans.
They escape it through:
-
Awareness
-
Small buffers
-
Reduced chaos
-
Emotional safety around money
-
Systems that work with real life
Progress is quiet. Gradual. Often boring.
And it works.
Habits Matter—but Context Matters Too
Money habits can keep people poor—but they are not the whole story.
Recognizing harmful habits isn’t about blame. It’s about regaining agency where possible, within real-world constraints.
If you see yourself in this article, that’s not a failure.
It’s clarity.
And clarity is where change begins.
Read next: Why You Overspend (And How to Stop)
Leave a Reply