Unpredictability Is the Most Exhausting Money Problem in America
Most conversations about money stress in America follow a familiar script. People talk about rising prices, stagnant wages, rent that keeps climbing, student loans that never seem to shrink, and the pressure to “do everything right” financially while the rules keep changing.
But beneath all of that is a quieter, more pervasive source of stress—one that doesn’t always show up in spreadsheets or surveys, yet shapes how millions of Americans think, feel, and behave every day.
That stress is unpredictability.
Not knowing what next month will cost.
Not knowing when a single expense will undo years of careful planning.
Not knowing whether today’s stability will still exist six months from now.
For many Americans, financial stress isn’t about being broke. It’s about never feeling safe.
When Stability Matters More Than Income
A surprising number of households earn what would traditionally be considered a “decent” income. On paper, things look manageable. Bills get paid. There may even be some money left over at the end of the month.
Yet the anxiety remains.
That’s because income alone does not create financial security. Stability does.
A household can function comfortably at a lower income if expenses are predictable. At the same time, even a strong salary can feel fragile if costs fluctuate without warning. The emotional difference between these two realities is enormous.
Predictability allows people to plan.
Unpredictability forces people to brace.
And bracing, over time, becomes exhausting.
The Constant State of “What If”
Financial unpredictability creates a background noise in people’s lives—a quiet but persistent worry that never fully turns off.
What if the car breaks down?
What if rent increases again?
What if insurance doesn’t cover what it should?
What if hours get cut?
What if one medical issue wipes out everything?
These questions don’t appear once. They repeat daily, shaping decisions large and small.
People delay vacations they could afford.
They hesitate to leave jobs they’ve outgrown.
They avoid long-term commitments.
They keep their lives smaller than they want them to be.
Not because they’re irresponsible—but because uncertainty trains people to prioritize survival over growth.
Why This Stress Is Hard to Name
Unpredictability is rarely discussed because it’s difficult to measure and easy to internalize.
It doesn’t show up as a single dramatic event.
It accumulates slowly, quietly, over time.
There’s also a cultural expectation in America that people should be able to “figure it out.” When something feels unstable, many assume the problem is personal rather than structural.
“If I were better at budgeting…”
“If I were more disciplined…”
“If I made smarter choices…”
But unpredictability is not a personal failure. It’s often the result of systems that shift costs onto individuals without warning—healthcare, housing, utilities, insurance, and employment being the most obvious examples.
When unpredictability becomes normal, people stop questioning the system and start questioning themselves.
The Emotional Toll of Never Feeling “Caught Up”
One of the most damaging effects of financial unpredictability is the inability to feel progress.
Even when people pay down debt.
Even when they save.
Even when they do everything “right.”
There’s always the sense that one unexpected expense could erase it all.
This leads to:
-
Chronic financial anxiety
-
Difficulty enjoying money, even when it’s available
-
A sense of being behind, no matter how hard one works
-
Emotional burnout tied to constant vigilance
Over time, this stress seeps into relationships, health, and self-esteem. Money becomes less about numbers and more about emotional safety.
How Unpredictability Shapes Spending and Saving Habits
From the outside, some financial behaviors may look irrational. In reality, they are often responses to instability.
People may:
-
Save aggressively but feel deprived
-
Avoid investing because they fear needing cash suddenly
-
Keep large balances in checking accounts “just in case”
-
Make impulsive purchases during moments of emotional exhaustion
-
Resist financial planning because it feels pointless
These behaviors are not signs of poor money management. They are defensive strategies developed in an unpredictable environment.
When the future feels unreliable, flexibility becomes more valuable than optimization.
The Role of Irregular Expenses
One reason unpredictability feels so overwhelming is that many costs aren’t monthly—they’re irregular, yet inevitable.
Car repairs.
Medical bills.
Insurance deductibles.
Home maintenance.
Family emergencies.
Seasonal expenses.
People often treat these as surprises, even though they happen repeatedly throughout life. When budgets focus only on monthly bills, these irregular costs feel like constant setbacks rather than expected parts of the financial cycle.
The emotional impact isn’t just the expense itself—it’s the feeling of being blindsided, again and again.
Why Financial Advice Often Misses the Point
Much mainstream financial advice assumes a level of stability that many Americans simply don’t have.
“Just build an emergency fund.”
“Just invest consistently.”
“Just stick to the plan.”
These suggestions aren’t wrong—but they’re incomplete.
They often fail to acknowledge:
-
Income volatility
-
Rising fixed costs
-
Healthcare uncertainty
-
Family obligations
-
Emotional fatigue
Without addressing unpredictability, advice can feel dismissive or unrealistic, making people feel even more disconnected from financial guidance meant to help them.
What Actually Helps Reduce This Stress
While individuals can’t control every aspect of an unstable system, certain shifts can reduce the emotional weight of unpredictability.
1. Planning for Reality, Not Perfection
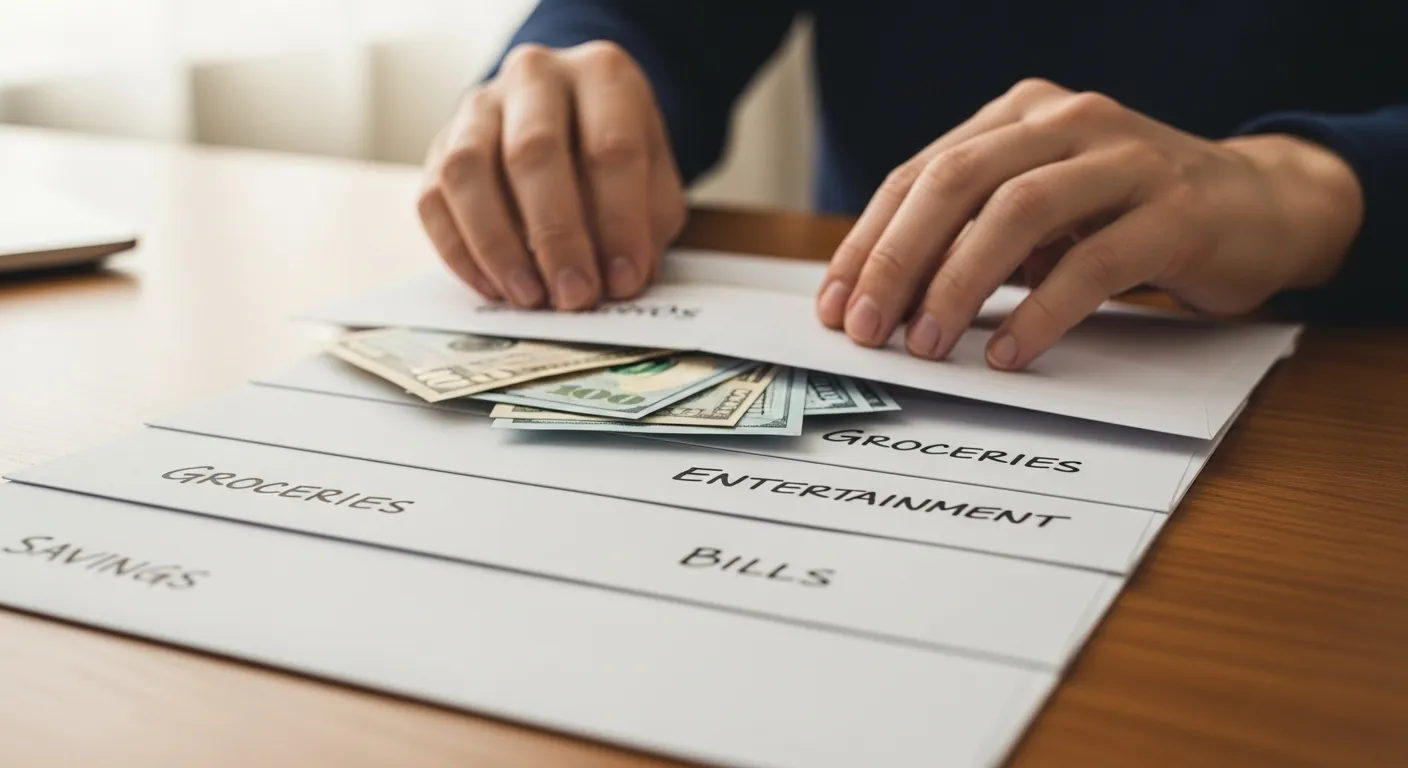
Instead of aiming for flawless budgets, people benefit from creating buffers—categories specifically meant for the unexpected.
This reframes irregular expenses from failures into normal occurrences.
2. Building Emotional Safety, Not Just Savings
An emergency fund isn’t about financial discipline. It’s about creating psychological breathing room.
Even a small buffer can dramatically reduce anxiety.
3. Designing Flexible Goals
Rigid financial timelines break easily under pressure. Flexible goals allow people to adapt without feeling like they’ve failed.
Progress doesn’t have to be linear to be real.
4. Letting Go of Comparison
Comparing financial stability across households ignores the invisible variables—health, family responsibilities, regional costs, and access to safety nets.
Stability is deeply personal.
The Quiet Truth About Financial Freedom
For many Americans, the ultimate goal isn’t wealth.
It’s predictability.
Knowing that bills won’t suddenly spike.
Knowing that one emergency won’t unravel everything.
Knowing that life has some margin for error.
This kind of stability allows people to think long-term, take healthy risks, and build lives that feel expansive rather than constrained.
Until unpredictability is acknowledged as a core source of financial stress, many people will continue to feel like they’re failing—even when they’re doing the best they can.
Naming the problem doesn’t fix everything.
But it removes the shame.
And sometimes, that’s the first real step toward financial peace.
Read next: When Small Purchases Become a Big Expense

Leave a Reply